JORGE R. REGALADO · MORTGAGE BROKER · MIAMI, FL
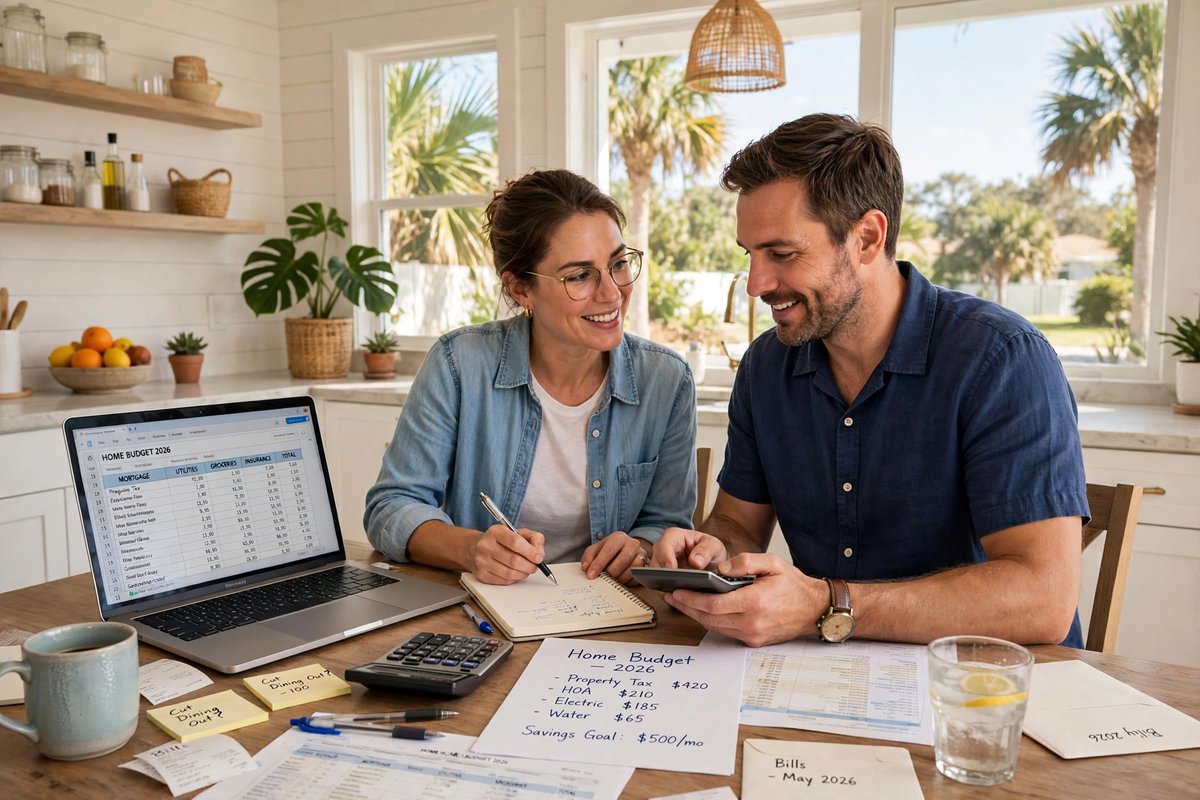
Online calculators love to give you a big, exciting number. Then reality shows up — in the form of a tax bill, an insurance premium, and an HOA statement — and the "affordable" house suddenly is not. In Florida especially, the loan is only part of the payment. Here is how to think about the full number before you fall in love with a listing in Tampa, Orlando, or Miami.
Principal and interest repay the loan itself. This is the only part the headline calculators tend to show, and the only part that stays fixed on a fixed-rate loan.
Property taxes are collected monthly into your escrow account and paid to the county on your behalf. Florida tax bills depend on the county, the home's assessed value, and whether exemptions like homestead apply — so the seller's old tax bill is not a reliable preview of yours.
Homeowners insurance is required by your lender and, in Florida, it is a serious line item. Premiums vary with the home's age, roof, construction, and location. Budget for it from the start, not as an afterthought.
Flood insurance may be required if the home sits in a designated flood zone, and some Florida buyers choose it even when it is not required. Either way, it belongs in the monthly math when it applies.
HOA or condo fees are common across Florida communities and condo buildings. They are not part of your mortgage, but your lender counts them when deciding what you can afford — and so should you.
Private mortgage insurance (PMI) applies to many conventional loans with less than 20% down. It is a real monthly cost, though often a temporary one that can end as you build equity.
Here is a worked example using round, made-up numbers to show the shape of a Florida payment:
For illustration only: these are hypothetical figures, not a quote, an offer, or a prediction of your costs — no interest rate is stated or implied. Your taxes, insurance, dues, and loan amount will be different, and that is exactly the point: a buyer who budgeted for "$2,350" would be $1,310 a month short. Affordability lives in the total.
As general guidance — not a law, and not a lender promise — financial planners and lenders often reference the 28/36 rule. It suggests keeping your total housing payment near or below 28% of your gross monthly income, and all of your monthly debt payments combined (housing, car, cards, student loans) near or below 36%.
For example, on a gross income of $10,000 a month, the 28% guideline points to a housing payment around $2,800. Different loan programs use their own debt-to-income limits, and strong savings or a larger down payment can change the picture. Treat 28/36 as a comfort check: a home you qualify for on paper should also be a home you can enjoy living in.
Affordability is not a price tag — it is a monthly payment you can carry calmly, in a Florida county, in a Florida insurance market. Get the full payment on any home you are serious about, with its real taxes, insurance, and dues, before you write the offer.
Want your real number? Try the closing-cost estimator at newloanco.com, or call Jorge R. Regalado at NEWLOANCO at 305-962-1170 and we will build the full payment together — no pressure, no obligation.
Jorge R. Regalado, Mortgage Broker, NMLS 1243458 · NEWLOANCO, NMLS 1369124 · 305-962-1170. Equal Housing Opportunity. This article is for general education only and is not a loan offer, rate quote, or commitment to lend. All loans are subject to credit review, underwriting approval, and program eligibility, which change over time.
© 2026 NEWLOANCO · 1000 Brickell Avenue, Suite 715-476, Miami, FL 33131 · 305-962-1170 · jr@newloanco.com · Company NMLS #1369124 · Jorge R. Regalado, MLO NMLS #1243458
Facebook Facebook — NEWLOANCO Page Instagram LinkedIn LinkedIn — NEWLOANCO X