JORGE R. REGALADO · MORTGAGE BROKER · MIAMI, FL
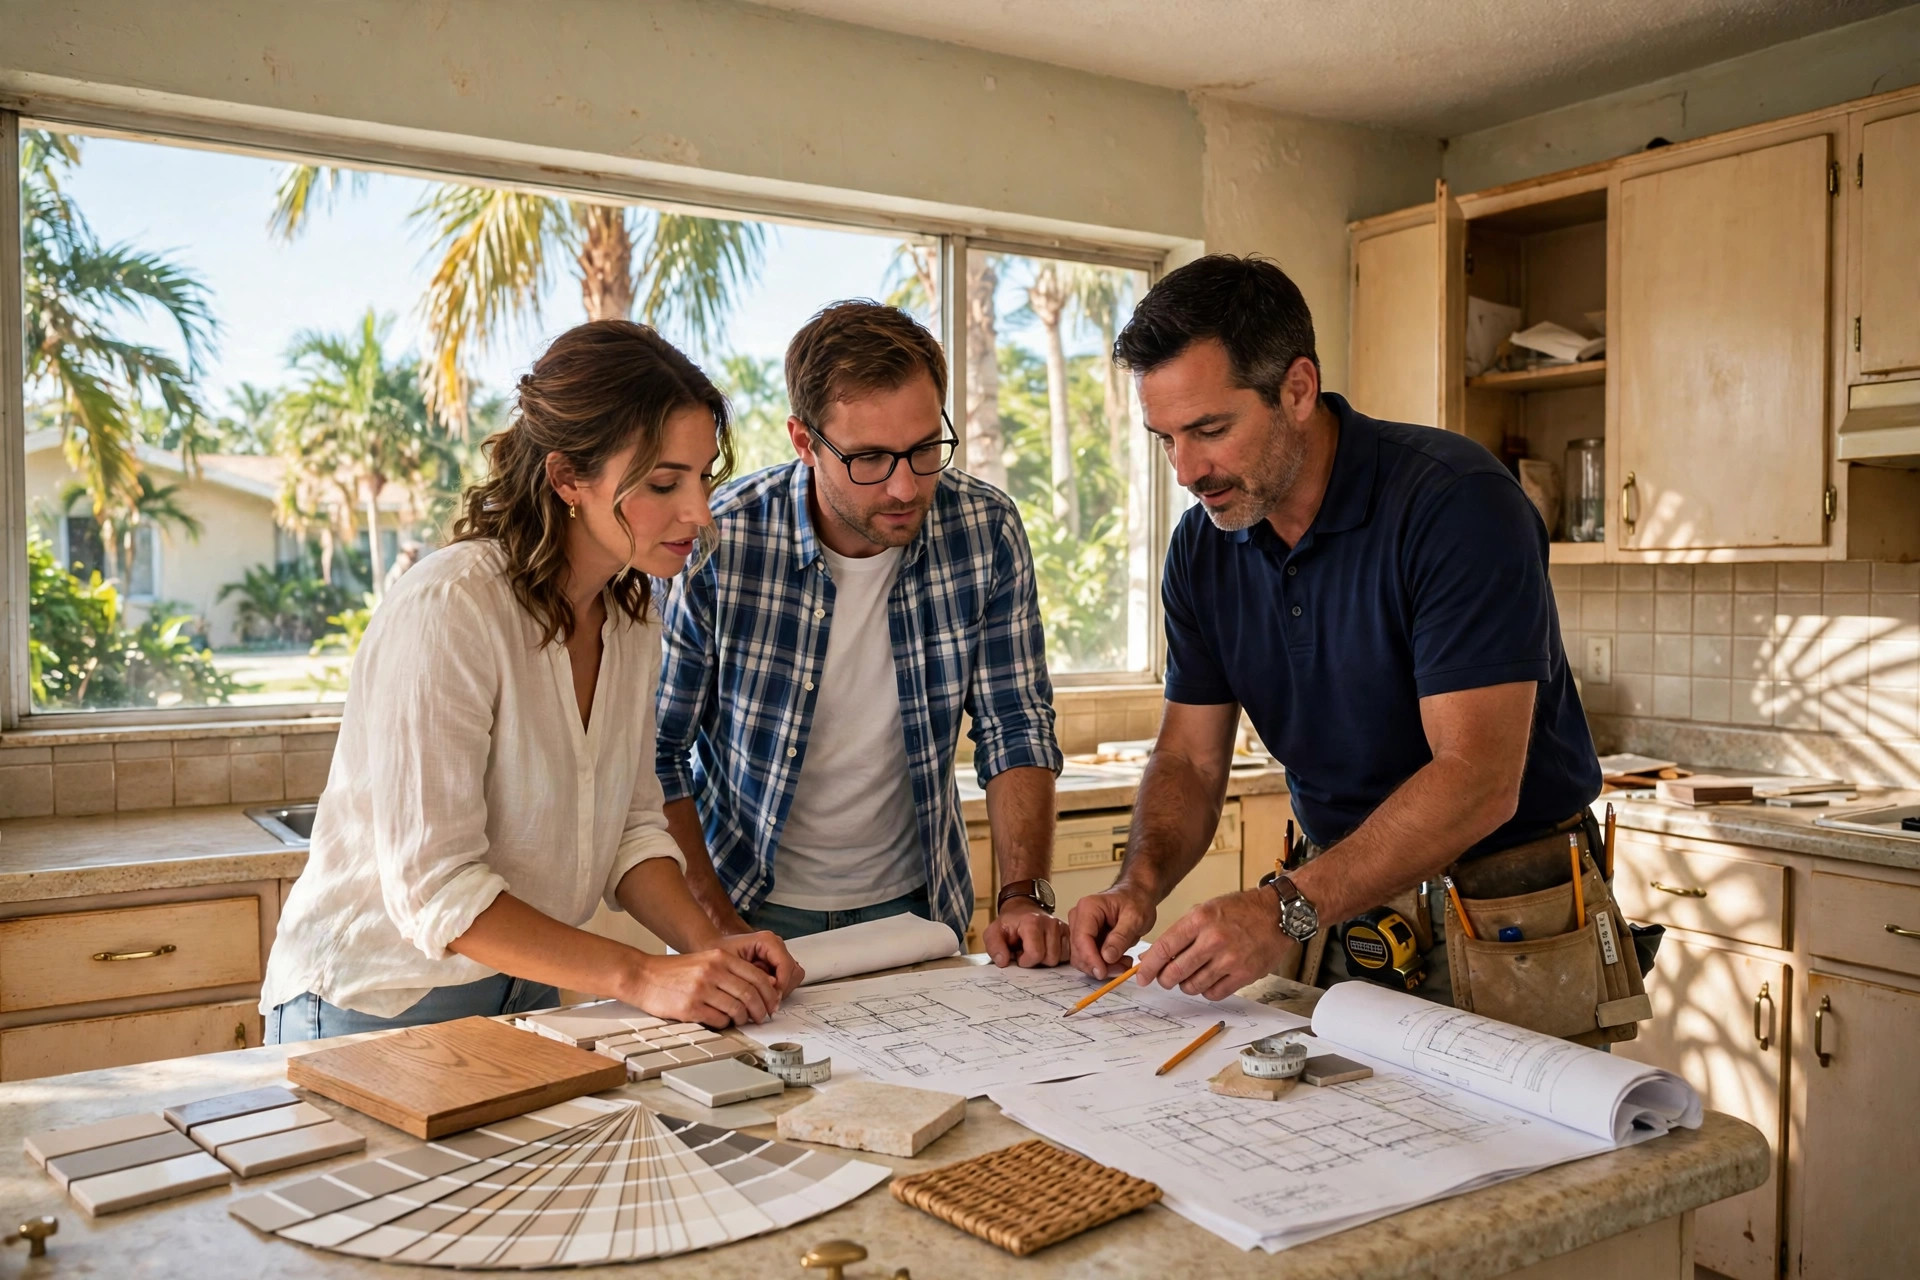
Some of the best-priced homes in Broward County, Palm Beach County, Jacksonville, and Southwest Florida are the dated ones: solid bones, tired kitchen, old systems. The problem is cash — after a down payment and closing costs, few buyers have enough left to renovate. A renovation loan solves that timing problem by financing the purchase and the planned repairs together, in one mortgage with one closing.
Instead of buying the home with one loan and then hunting for a second loan, a credit line, or cash for repairs, you borrow for both at once. The loan amount is built from the purchase price plus the approved renovation budget, and you make one monthly payment from the start. That structure matters in Florida, where an older home may be well located and fairly priced precisely because the next owner has to do the work.
On the FHA 203(k) track, the Limited version covers minor remodeling and nonstructural repairs, with total rehabilitation costs capped at $75,000 and no consultant required. The Standard version handles major or structural work — it requires at least $5,000 in eligible improvements and a HUD-approved 203(k) consultant who prepares the work write-up and cost estimate. Conventional renovation options follow a similar one-loan design and can finance renovation costs up to 75% of the home's as-completed value under their program rules. Which track fits depends on the scope of work, your down payment, and your credit profile — not just the size of the bid — and every version is subject to eligibility and program guidelines.
Because the lender is lending against the home you are creating, not only the one you toured. The appraiser reviews your plans and contractor bid and values the property as completed. That is what lets the repair budget fit inside the mortgage at all. It also imposes discipline: the finished value has to support the total loan, so a renovation that costs far more than it adds in value can shrink what you may borrow. Choose improvements the market rewards — working systems, a functional kitchen and baths, and sound structure — before purely personal upgrades.
At closing, the purchase money goes to the seller and the renovation money goes into a repair escrow account. Your contractor is then paid in stages, called draws, as work is completed and inspected — the FHA track allows a limited number of draw requests per project, and a portion may be held back until the final inspection confirms everything is finished. Work must be completed inside a set window, up to nine months on the Limited FHA track and up to twelve months on the Standard track. Money follows finished work, not promises, and change orders need approval before they are spent.
Three things, early. First, a properly licensed Florida contractor who will provide an itemized written bid before closing — renovation loans are built on paperwork, and a verbal estimate will not carry a file. Second, permits and local rules: structural, electrical, and roofing work in Florida generally needs permits and inspections, and your timeline should allow for them. Third, insurance: get a quote on the specific property early, because an older roof or older systems can change the cost of coverage while you renovate. Build a contingency reserve for surprises into your budget, and ask whether any down-payment help you hope to use — Florida Housing, Hometown Heroes, or county assistance, all subject to eligibility and funding availability — can work alongside your renovation plan before you count on layering it.
Eyeing a Florida fixer-upper? Bring us the listing and a rough repair list before you offer — we will map which renovation track the project fits and what the finished-home math looks like. Home Starts With Ease. Call Jorge R. Regalado at NEWLOANCO at 305-962-1170, request a closing-cost estimate on the site, or start online: Apply Now.
Jorge R. Regalado, Principal Loan Originator, NMLS #1243458 · NEWLOANCO, NMLS #1369124 · 305-962-1170. Equal Housing Lender. This article is for general education only and is not a loan offer, rate quote, or commitment to lend. All loans are subject to credit review, underwriting approval, and program eligibility. Assistance amounts, terms, income limits, and funding availability change and are confirmed at application.
© 2026 NEWLOANCO · 1000 Brickell Avenue, Suite 715, Miami, FL 33131 · 305-912-7759 · jr@newloanco.com · Company NMLS #1369124 · Jorge R. Regalado, MLO NMLS #1243458
Facebook Facebook — NEWLOANCO Page Instagram LinkedIn LinkedIn — NEWLOANCO X